The AnewZ Opinion section provides a platform for independent voices to share expert perspectives on global and regional issues. The views expressed are solely those of the authors and do not represent the official position of AnewZ
The petrodollar system, which has anchored the U.S. dollar’s dominance in global energy markets for five decades, is showing clear signs of strain. Pressures from geopolitical tensions and shifting trade practices are accelerating moves away from dollar-based oil transactions.
The 1974 agreement between the United States and Saudi Arabia - under which Riyadh priced oil exports in dollars and recycled surpluses into U.S. Treasuries in exchange for security guarantees - created a self-reinforcing cycle that sustained global demand for the currency. In 2026, however, that arrangement is under pressure from multiple directions.
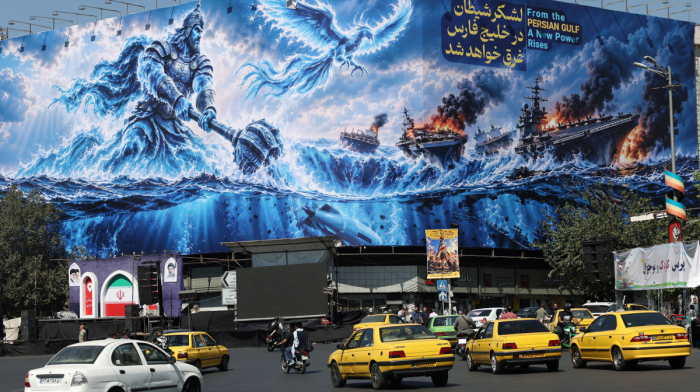
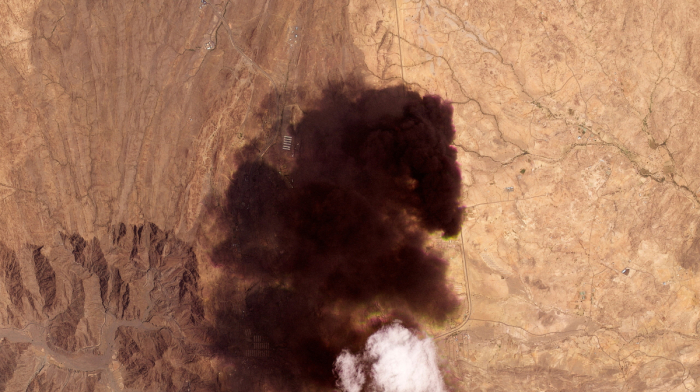
Iran’s restrictions on shipping through the Strait of Hormuz, which carries 20–21 million barrels per day of crude and refined products (roughly 20–27% of global seaborne oil trade), have accelerated moves towards alternative currencies. Data from March 2026 show Brent crude rising from around $66 per barrel before the latest escalation to peaks above $120, while insurance premiums for Gulf tankers have jumped by as much as 500% in some cases. These developments coincide with a broader, gradual diversification in oil settlement currencies that predates the current conflict.
The foundations and emerging cracks
The petrodollar system reached its height in the decades following the 1970s oil crisis. Oil was overwhelmingly priced and settled in dollars, creating automatic demand for the currency even as the United States ran persistent current account deficits. Gulf Cooperation Council (GCC) states pegged their currencies to the dollar and accumulated reserves that were largely recycled into U.S. assets. As of late 2025, Saudi Arabia and the UAE together held approximately $250 billion in U.S. Treasuries, while GCC sovereign wealth funds managed more than $6 trillion overall, much of it dollar-denominated.
Recent figures, however, point to gradual erosion. The U.S. dollar’s share of global foreign exchange reserves stood at 56.9% in the third quarter of 2025, down from a peak of 72% in 2001, according to IMF data. The decline is partly mechanical - driven by exchange rate movements - but also reflects active diversification.
Saudi Arabia allowed non-dollar payments for oil as early as 2024, after the 50-year exclusive pact with Washington expired. China, which buys roughly four times more Saudi oil than the United States, has settled portions of its imports in renminbi. In the first two months of 2026, Iranian oil deliveries to China continued via “dark fleet” tankers using the mBridge platform, which processed more than $55 billion in transactions by late 2025, with the digital yuan accounting for around 95% of volume in tested corridors.
The Hormuz situation has sharpened these trends. Iran has indicated that tankers complying with yuan-denominated contracts receive preferential passage, while those tied to dollar-based Western sanctions face higher risks. This bifurcation has created a de facto two-tier market: dollar-priced oil carries a war-risk premium, while yuan-settled cargoes move with a degree of protection. The result is not an immediate collapse of the petrodollar, but a measurable loss of exclusivity.
Currency diversification and alternative mechanisms
De-dollarisation in energy trade is proceeding incrementally rather than through outright rejection. BRICS members - now expanded to include Saudi Arabia and Iran - have increased the use of local currencies for bilateral oil and gas deals. Russia has settled large volumes with India in rupees, while China has expanded renminbi-denominated contracts with multiple Gulf suppliers. The Cross-Border Interbank Payment System (CIPS), China’s alternative to SWIFT, handled a growing share of energy-related payments in 2025, though it still represents only a fraction of total global flows.
These shifts are driven largely by practical considerations. U.S. sanctions on Russia after 2022 highlighted the risks of over-reliance on a single currency and payment infrastructure. For Gulf producers, selling to Asia - which absorbs the majority of their exports - makes currency diversification a hedging strategy rather than an ideological shift. Saudi Arabia’s Vision 2030 explicitly includes financial autonomy, and the UAE has similarly tested non-dollar oil trades.
The United States remains a net energy exporter, reducing its direct dependence on Middle Eastern oil. Yet the petrodollar’s role in financing U.S. deficits remains significant. National debt crossed $39 trillion in March 2026, with annual interest payments projected to exceed $1 trillion. Foreign demand for Treasuries, partly sustained by petrodollar recycling, helps keep borrowing costs manageable. Any sustained reduction in that demand would raise yields and increase the fiscal burden, even if the shift occurs gradually.
Implications for the international monetary order
The petrodollar’s erosion does not mean the dollar is about to lose its reserve status overnight. The currency still accounts for the majority of global trade invoicing and financial transactions and no single alternative has the depth or liquidity to replace it fully. However, the system is becoming less automatic. The 2026 Hormuz crisis has illustrated how control over physical oil flows can influence currency preferences in real time. Prediction markets in March assigned meaningful probabilities to a further acceleration in non-dollar oil settlements if the standoff persists.
For the United States, the challenge is to manage this transition without triggering abrupt shocks to borrowing costs or financial stability. For other economies, the shift creates space for greater monetary autonomy but also introduces new volatility and transaction costs in the short term. Developing countries that have accumulated dollar-denominated debt face higher servicing burdens when commodity prices fluctuate, while those able to settle trade in local currencies gain flexibility.
The current episode around the Strait of Hormuz serves as a stress test. Whether the petrodollar system ultimately unravels or adapts to a more fragmented global order will depend on how producers, consumers and financial markets respond to the incentives created by today’s geopolitical pressures. The figures - $39 trillion in U.S. debt, a 56.9% dollar reserve share, and $55 billion in mBridge volume - point to a system under measurable, if gradual, strain.





What is your opinion on this topic?
Leave the first comment