As Israelis head to the polls on Tuesday, 27 October, the Israeli economy faces a paradox; soaring stocks and a stronger currency alongside rising public debt and billions of dollars in war costs. What do the figures reveal about the challenges awaiting the next government?
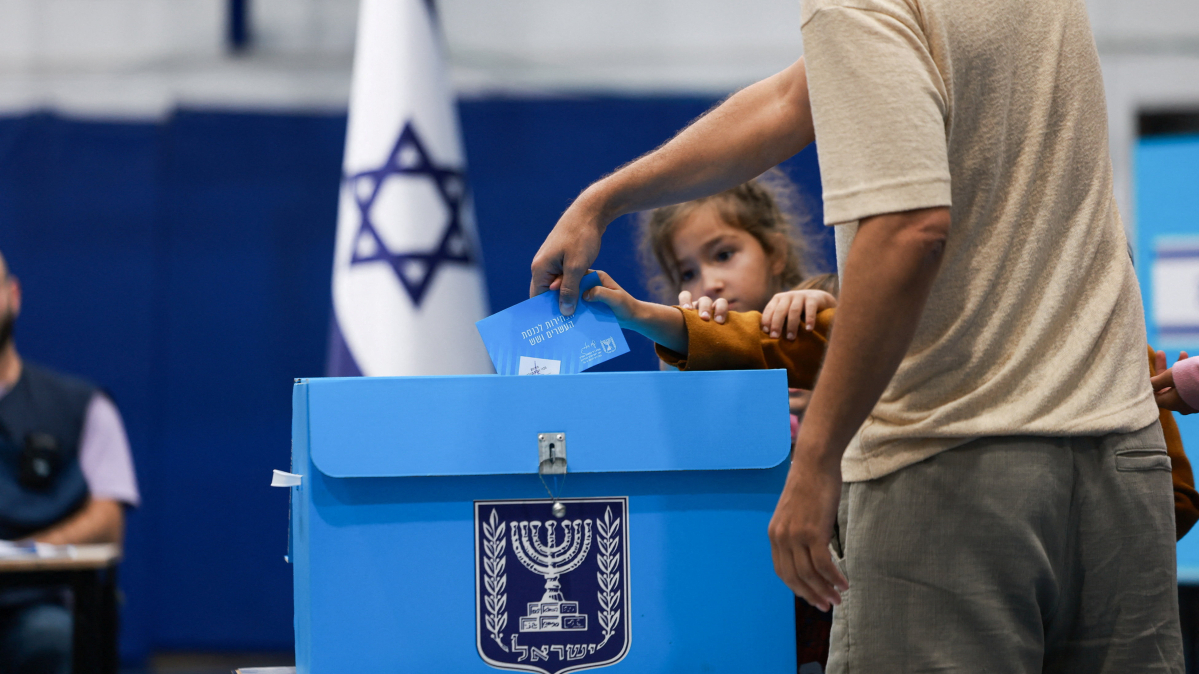
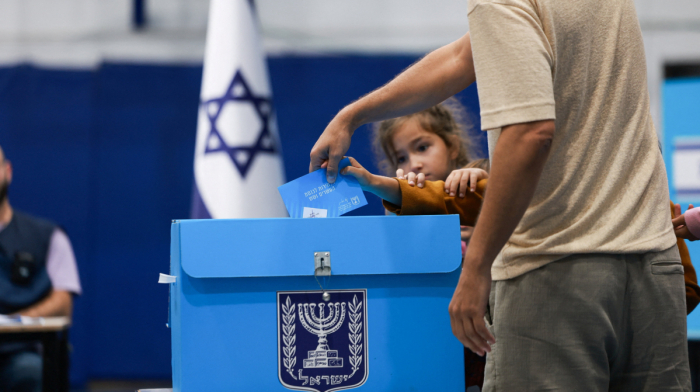
Israelis began voting on 27 October in the first parliamentary election since the Hamas-led attacks of October 2023 and the regional conflicts that followed.
The vote will determine the composition of the next parliament, with Prime Minister Benjamin Netanyahu's Likud party facing opposition parties including former military chief Gadi Eisenkot's Yashar.
Beyond the battle for political power lies a pressing economic question: how has Israel weathered three years of conflict, and what financial challenges await the next government?
The figures paint a contrasting picture: booming financial markets alongside mounting pressure on public finances.
Israeli stocks surge despite three years of conflict
Since October 2023, Israeli stocks have risen around 130 per cent, compared with an 80 per cent gain on Wall Street, according to Reuters.
The Israeli shekel has also strengthened by approximately 25 per cent over the same period, making it one of the world's strongest-performing currencies.
Israeli government bonds have delivered returns of around 30 per cent over the past two years, more than double the performance of major emerging-market bond indexes.
Technology, defence exports and demand for artificial intelligence-related products have helped support that performance.
Lior Yochpaz, chief investment officer at Israeli insurer Menora Mivtachim, told Reuters that businesses had continued to prosper despite political upheaval, disputes over judicial reforms and regional conflict.
The strength of Israeli companies, however, does not tell the whole economic story.
The $55 billion war price tag
Three years of conflict have cost Israel's economy more than $55 billion, according to Reuters estimates.
Government debt has climbed towards 70 per cent of gross domestic product, up roughly 10 percentage points since 2022.
Defence spending has approximately doubled to 8 per cent of GDP, while the fiscal deficit has widened significantly.
The mounting costs are putting pressure on public finances, with rising debt repayments and military expenditure competing with other government priorities.
The Bank of Israel's latest forecast, published on 21 October, projects a budget deficit of 4.4 per cent of GDP in 2026 and 4.6 per cent in 2027.
It also forecasts government debt at approximately 68 per cent of GDP by the end of this year.
The central bank has warned of uncertainty surrounding defence spending, government revenue and future fiscal decisions.
Why strong growth figures need context?
The Bank of Israel expects the economy to expand by 5.6 per cent in 2026 and 7.5 per cent in 2027.
Yet those headline figures include production overseas, which makes a substantial contribution to the forecast.
Excluding that activity, projected growth falls to 3.4 per cent this year and 5.1 per cent next year.
The distinction is important, as strong headline growth does not necessarily translate into an equivalent expansion of economic activity taking place inside Israel.
Technology remains a major source of strength. According to Reuters Breakingviews financial commentary, the sector accounted for 18 per cent of GDP in 2025 and approximately half of the economy's growth.
That concentration also raises longer-term questions about the breadth of the country's tax base and its ability to finance higher defence spending.
Can the election move the markets?
History suggests Israeli financial markets can experience volatility around elections, although the outcome varies.
Research by the Tel Aviv Stock Exchange covering the previous 10 elections found that volatility in leading share indexes rose by as much as 45 per cent in the weeks after voting compared with a typical week.
Initial losses were generally recovered within a month, with indexes recording an average gain of about 1.7 per cent.
Over the year following elections, the TA-125 index returned an average 16.4 per cent, compared with a longer-term annual average of 11.5 per cent.
These are historical averages, not forecasts for Tuesday's vote.
In an August assessment, JPMorgan estimated that the election could move the shekel by as much as 3 per cent in either direction, depending on political developments.
The bank's scenarios reflected possible changes in investor perceptions, rather than certainty about the election result.
Consequences extend beyond Israel
Regional markets are also watching the election for potential implications for diplomatic relations and security.
Jean-Charles Sambor of investment firm TT International told Reuters that a shift in Israel's political leadership could reshape investors' assessment of regional risk.
He pointed to Lebanese government bonds as a potential investment opportunity if regional conditions improve.
The assessment highlights how political developments in Israel could influence investor sentiment beyond its borders, although any improvement in regional stability remains uncertain.
The immediate question is who can form a government in Israel's fragmented parliament. The broader economic test will be how that government manages defence costs, borrowing and investment while regional uncertainty continues.
For voters, businesses and investors across the region, the election result may settle the political contest, but the economic reckoning will continue.




What is your opinion on this topic?
Leave the first comment